

Macro heavy week

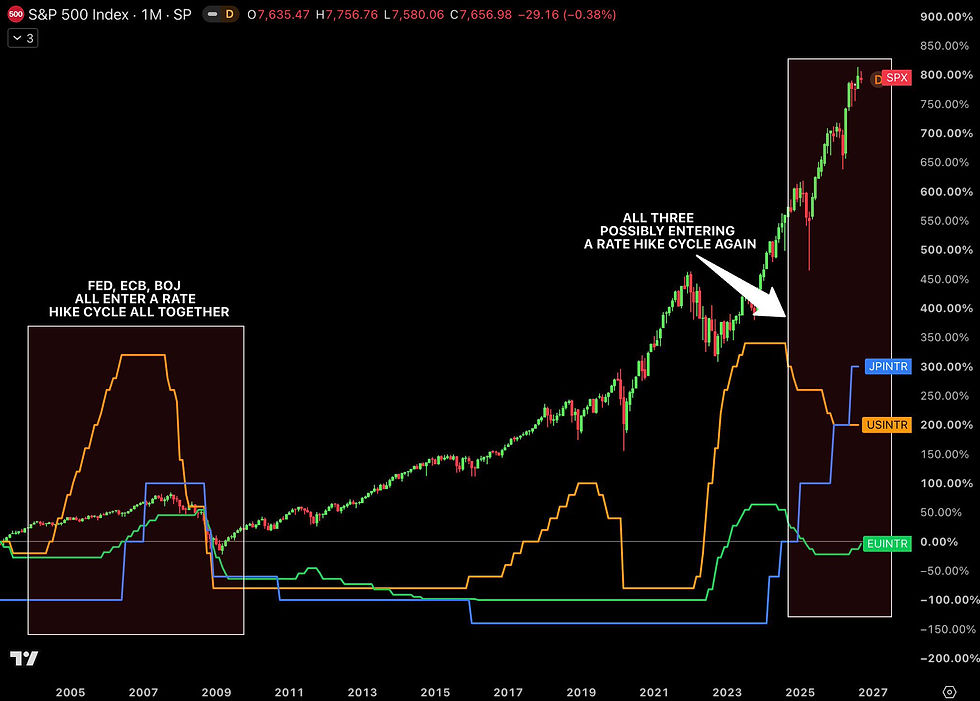
This is one of the more unusual macro weeks in years: the Fed, the ECB and the BOJ are all leaning toward tighter policy at the same time, while Brazil's Copom is expected to keep cutting. Here's the picture heading into a heavy run of central bank decisions.
🇺🇸 𝗨𝗻𝗶𝘁𝗲𝗱 𝗦𝘁𝗮𝘁𝗲𝘀
August CPI came in hot: headline +0.4% m/m (3.4% y/y), core +0.3% m/m (2.4% y/y), both a touch above forecasts. Gasoline (+3.9% m/m, +27.4% y/y) did most of the damage as energy prices reaccelerated. The Fed decides September 15-16, and futures markets are now pricing a real chance of a hike rather than the cut many expected earlier this year — a sharp repricing driven almost entirely by the energy shock, not underlying demand.
🇪🇺 𝗘𝘂𝗿𝗼𝘇𝗼𝗻𝗲
Headline HICP jumped to 3.3% y/y in August from 2.9% in July — the highest since 2023/24 — again led by energy (+14.3% y/y). Core inflation is actually easing (~2.2-2.4%), but the headline surge was enough for the ECB to hike 25bps to 2.50% on September 10, a reversal after a year of cuts.
🇯🇵 𝗝𝗮𝗽𝗮𝗻
The BOJ hiked to 1.00% in June and held in July, but Tokyo inflation is accelerating again and swaps markets now price an ~85% chance of another hike (to 1.25%) at the September 17-18 meeting. USD/JPY near 160 keeps the yen — and the risk of intervention — front and center.
🇧🇷 𝗕𝗿𝗮𝘇𝗶𝗹
The outlier. August IPCA came in negative (deflation), clearing the way for a fifth straight Selic cut — Copom is expected to trim 25bps to 13.75% on the same days as the Fed decision. Inflation is still running above the 4.5% target ceiling (~5% expected for 2026), but the disinflation trend has given the central bank room to keep easing even as developed-market peers turn hawkish.
𝗪𝗵𝘆 𝗶𝘁 𝗺𝗮𝘁𝘁𝗲𝗿𝘀 𝗳𝗼𝗿 𝗺𝗮𝗿𝗸𝗲𝘁𝘀
This is an energy-driven inflation shock (Middle East tensions), not a demand-driven one — and central banks are responding to the headline number, not necessarily the underlying trend. That creates real divergence risk:
• Rate-sensitive equities and duration assets face renewed pressure if the Fed/ECB/BOJ all tighten into a growth slowdown
• FX volatility picks up — USD/JPY, EUR/USD and BRL all have live catalysts this week
• Brazil's easing-while-the-world-tightens stance keeps carry trades interesting, but leaves the real exposed if the rate gap narrows faster than expected
• Bond markets will be parsing whether this is a one-quarter energy spike or the start of a stickier inflation regime
Three central bank decisions in three days (Fed and Copom on Sept 15-16, BOJ on Sept 17-18, plus the BoE). Buckle up.
Want to know more? You can register for free at Fund@mental.
#iamfundamental #soyfundamental #wealthmanagement #familyoffice #financialadvisor #financialplanning #policymistake #ratecut #stagflation


Comments